
When cost is uncertain, it’s natural to hesitate. But with varicose veins, insurance questions shouldn’t get in the way of addressing your medical concerns. A proper evaluation can determine the appropriate treatment and what documentation your insurance plan may require. From there, the financial side of the equation will become much more transparent. If you’ve been holding off because you’re unsure whether varicose vein treatment is covered by insurance, understanding the process is the first step towards moving forward. In this guide, we’ll explain what determines coverage, what you can expect to pay, and how to get started.
Key Takeaways
- Insurance generally covers treatment for medically necessary, symptomatic varicose veins, which differs from treatment performed for cosmetic reasons.
- Many coverage policies require documentation of symptoms and a trial of conservative treatment, such as compression therapy, before certain procedures can be approved.
- Most doctors use a duplex ultrasound to evaluate the veins, identify abnormal blood flow, and help determine the appropriate treatment.
- Your coverage, deductible, coinsurance, and authorization requirements depend on your specific health plan, so out-of-pocket costs may vary from patient to patient.
- The Kimmel Institute offers free vein screening evaluations and provides hands-on support to navigate the insurance process before you move forward.
What Makes Vein Treatment “Medically Necessary”
The key question for insurance is often whether your varicose veins are causing a medical problem, rather than simply being visible. Varicose veins are a common manifestation of chronic venous disease and can cause symptoms ranging from leg discomfort and heaviness to swelling and skin changes. In fact, StatPearls reports that varicose veins occur in up to 30% of the general population.
So, what does “medically necessary” actually mean? In simple terms, it means treatment is being considered because a vein condition is affecting your health, comfort, or normal daily activities. Symptoms may include aching or pain, leg heaviness or fatigue, swelling, burning or itching, skin changes, or bleeding from a varicose vein. Because symptoms can vary from person to person, a medical evaluation is an important first step in understanding what is happening beneath the surface.
By contrast, treatment performed solely to improve the appearance of visible veins, or treatment of asymptomatic varicose veins, is generally considered cosmetic. Spider veins, for example, are typically treated for cosmetic reasons and are not covered under current Medicare guidelines.
The appearance of your veins alone doesn’t always tell the whole story. A thorough evaluation can help determine whether an underlying vein problem is contributing to your symptoms and whether treatment may be considered medically necessary under your insurance plan.
How Insurers Decide What to Cover
If you’re considering treatment for varicose veins, you may be wondering what your insurance company actually looks for before approving a procedure. While requirements vary by plan, the process typically comes down to a few key pieces of information: your symptoms, your diagnosis, and whether conservative treatment has been attempted.
Documented Symptoms
The first step is establishing that your varicose veins are causing a medical problem. Your healthcare provider will typically document symptoms such as aching or pain, heaviness or fatigue in the legs, swelling, skin changes, or bleeding from affected veins.
This documentation helps show how your vein condition is affecting your health and daily life. Simply having visible varicose veins, without symptoms or other evidence of a medical problem, may not meet your insurance plan’s criteria for medically necessary treatment. That’s why it’s essential to receive a thorough medical evaluation.
The Duplex Ultrasound Requirement
A duplex ultrasound is a painless, noninvasive test that evaluates how blood is moving through your veins. It can identify venous reflux, which happens when blood flows backward because the valves inside the veins aren’t working properly.
The ultrasound also gives your provider a clearer picture of your vein anatomy and helps rule out other potential causes of your symptoms. In addition to being required by many insurance plans before approving treatment, the ultrasound is a key part of the diagnostic process and selecting an appropriate treatment approach.
The Conservative Therapy Trial
Depending on your insurance plan, you may also need to try conservative treatment before a procedure can be approved. Conservative therapy refers to nonsurgical measures that may help manage symptoms, such as wearing compression stockings, staying active, exercising, and elevating your legs.
For certain varicose vein procedures, current Medicare coverage guidelines require documentation that conservative treatment has been tried for a specified period and that symptoms have persisted. Treatment of asymptomatic varicose veins, or treatment when the required conservative therapy has not been completed, may be considered cosmetic and excluded from coverage.
This step is generally a standard part of the treatment process. Your provider can help you understand what your particular plan requires and make sure the appropriate information is documented.
What’s Considered Cosmetic
Insurance generally distinguishes between treating a medical vein problem and treating veins solely for appearance. Treatment of spider veins is typically considered cosmetic, as is treatment of varicose veins that are not causing symptoms or other documented medical problems.
Coverage requirements vary by insurance plan. Some insurers may require specific documentation, diagnostic testing, or prior authorization before approving treatment for symptomatic varicose veins. If you’re unsure of where to start, a medical evaluation can help clarify whether your symptoms may meet your plan’s criteria and what steps may be required before treatment.
Not sure if your symptoms would qualify? A free screening at the Kimmel Institute can help you find out.
What Affects Your Specific Coverage
Insurance coverage for varicose vein treatment isn’t one-size-fits-all. Even when treatment is considered medically necessary, your specific plan may have its own requirements for documentation, conservative treatment, prior authorization, and out-of-pocket costs.
Medicare vs. Private Insurance
Medicare’s coverage guidelines can provide a useful example of how insurers determine medical necessity. As explained above, current Medicare guidelines require specific documentation and, for certain procedures, a trial of conservative treatment before treatment may be covered. The required timeframe and other criteria can vary depending on the procedure.
Private insurance plans and Medicare Advantage plans may follow different rules. Some may require a longer or shorter period of conservative treatment, additional documentation, a referral, or prior authorization before treatment can move forward.
That’s why it is important to check the requirements of your specific plan rather than relying on general information about insurance coverage. Your provider’s office can also help you understand what documentation is needed and what questions to ask your insurer.
Prior Authorization
Prior authorization is the process of getting approval from your insurance company before a planned procedure is performed. If your plan requires prior authorization, the insurer will review your medical information to determine whether the treatment meets its coverage criteria.
This may include documentation of your symptoms, results from your duplex ultrasound, your diagnosis, and records showing that you completed any required conservative therapy. Your provider’s team can help gather the necessary documentation and guide you through the authorization process, so you know what to expect at each step.
Your Out-of-Pocket Costs
Even when a procedure is covered by insurance, you may still have some out-of-pocket costs. Your deductible, copayments, coinsurance, and other plan benefits can all affect what you ultimately pay.
For example, Medicare.gov explains that after the Part B deductible is met, patients generally pay 20% of the Medicare-approved amount for covered outpatient medical and surgical services. Your actual costs may differ depending on your coverage, the services you receive, and whether additional benefits or cost-sharing rules apply.
That’s why it helps to understand your benefits before treatment. At the Kimmel Institute, transparent conversations about costs are part of the patient experience. Our team can help you understand what your insurance may cover, what documentation may be required, and what you may be responsible for paying. Most importantly, you’ll have an opportunity to ask questions and discuss your options before moving forward.
Steps Before You Schedule Treatment
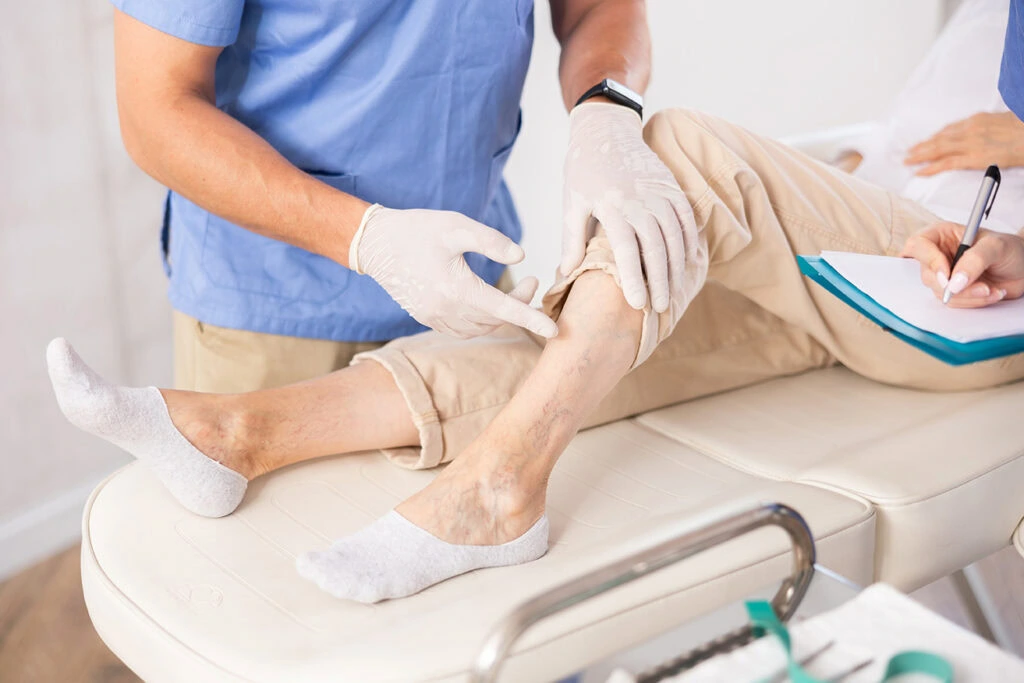
If you’re ready to explore treatment but unsure where to begin, the process can be broken down into a few straightforward steps. Starting with an evaluation and gathering the right documentation can help you and your provider determine what treatment may be appropriate and what your insurance plan requires.
Get a Symptom Evaluation
Start with a professional evaluation rather than trying to determine on your own whether your symptoms qualify for covered treatment. Your provider can assess your veins, discuss symptoms such as aching, heaviness, swelling, or skin changes, and determine whether further testing is appropriate. A thorough evaluation establishes a medical record documenting your symptoms and their impact, in addition to giving you an opportunity to ask questions and better understand what may be causing your symptoms.
Complete the Ultrasound Diagnosis
If an underlying vein problem is suspected, your provider will likely recommend a duplex ultrasound. This painless, noninvasive test shows how blood is moving through your veins and can identify problems such as venous reflux. These results become an important part of your medical record and provide a key part of the diagnostic documentation your insurance plan requires and will review before treatment can be considered.
Document the Conservative Therapy Trial
If your insurance plan requires conservative treatment before a procedure, keep track of what you have tried and when you started. This may include compression stockings, exercise, leg elevation, or other measures recommended by your provider. The timeline matters because some plans require conservative therapy for a specific period before treatment can be considered. Keeping a record of when you started and how your symptoms responded can help your provider document that requirement when submitting your treatment for insurance review.
Let the Practice Handle Prior Authorization
If prior authorization is required, you don’t have to navigate the process alone. The Kimmel Institute’s team can help coordinate the documentation your insurance company needs, including your medical history, ultrasound findings, and records of conservative treatment.
Our team will help you understand what documentation has been submitted and keep you informed about what to expect next. At the Kimmel Institute, our team takes the time to guide you through the insurance process personally, answer your questions, and make sure you feel informed and supported at every step.
The Kimmel Institute can walk you through the documentation and insurance process step by step.
Conclusion
If you have varicose veins, one of the first questions you may have is whether your insurance will cover treatment. In most cases, the answer comes down to medical necessity, which is demonstrated by symptoms such as pain, heaviness, swelling, or skin changes. Your plan may also require an ultrasound, a trial of conservative treatment, or prior authorization.
Knowing what your insurance plan requires can make the process much easier to navigate. At the Kimmel Institute, our team is here to evaluate your symptoms, explain your treatment options, and help you understand the insurance process.
If you’re unsure whether your symptoms qualify, a free screening is an easy first step. At the Kimmel Institute, Dr. Kimmel and our team have been in practice in South Florida since 1991, providing knowledgeable vein care with a personal touch.
FAQs: Is Varicose Vein Treatment Covered by Insurance?
What does “medically necessary” mean for vein treatment insurance coverage?
“Medically necessary” means treatment is being recommended for a documented medical problem, rather than appearance alone. Symptoms such as pain, swelling, heaviness, skin changes, or bleeding are evidence of medical necessity. Insurers use this distinction when determining whether a treatment meets their coverage requirements.
How do I start the insurance approval process for vein treatment?
Begin with a comprehensive evaluation of your symptoms and a duplex ultrasound to assess blood flow and identify underlying venous disease. If your plan requires conservative treatment, keep documentation of these treatments. Your provider can then submit the necessary records for prior authorization.
How much will I pay out of pocket if my treatment is covered?
Covered treatment can still involve out-of-pocket costs, including a deductible or coinsurance. For Medicare Part B, patients generally pay 20% of the Medicare-approved amount after meeting their deductible. A transparent cost conversation with the Kimmel Institute can help clarify your expected expenses before you schedule treatment.
Does insurance ever cover spider veins or cosmetic vein treatment?
Most insurance plans, including Medicare, typically don’t cover treatment performed solely for cosmetic reasons. Spider veins and asymptomatic varicose veins are generally classified as cosmetic because they don’t cause documented medical symptoms.
What if my insurance denies my claim for vein treatment?
In many cases, an insurance denial simply means additional documentation is needed to confirm that treatment meets the plan’s coverage requirements. Your provider can review the insurer’s request, provide any necessary records, and help determine whether additional documentation, a longer conservative therapy trial, or an appeal is appropriate.